
Last Updated on September 21, 2026 by Taya Ziv
Venture capital just had the best six months in its recorded history. That sentence is true, and for most founders reading it, it is almost useless.
Here is the number everyone has been repeating since the H1 reports landed in July 2026. Per Crunchbase’s count of global startup investment in the first half of 2026, startups raised a record 510 billion dollars worldwide. That is more than the 440 billion invested in all of 2025 put together, and it blows past the old half-year record of 375 billion set at the very top of the 2021 bubble. Every headline runs some version of the same word. Boom. Records. Best ever.
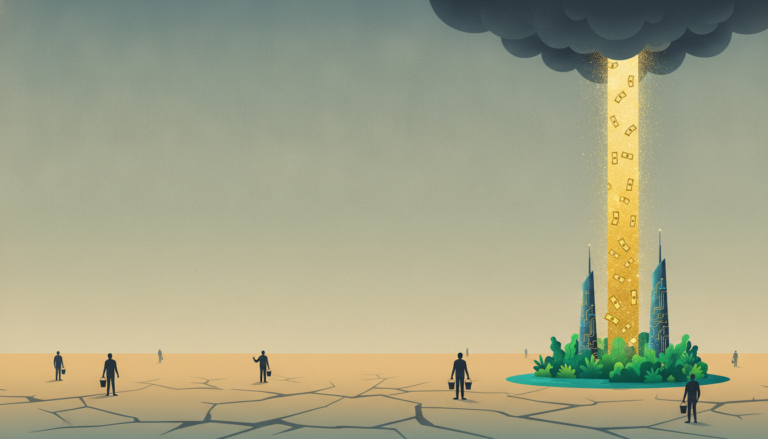
Now here is the number nobody puts in the headline. In that same Crunchbase data, two companies, OpenAI and Anthropic, took 217 billion dollars of it between them. That is 43 percent of every venture dollar raised on the entire planet, landing at two addresses in the Bay Area. Switch to PitchBook’s count of the US market, which is a different vendor with a different methodology, and it gets starker: of the 412.7 billion dollars deployed in the United States, the PitchBook-NVCA Q2 2026 Venture Monitor puts 355.9 billion into AI companies. Eighty six cents on the dollar. So before you let that record number set your expectations for your own raise, understand what it is actually describing. It is not your year. It might not even be a good one.
The record is a lie of averages
There is an old joke economists use to explain averages. Bill Gates walks into a bar, and on average, everyone inside is a billionaire. Nothing changed for the guy nursing a beer in the corner. The number just stopped meaning anything about him.
That is the 2026 funding market. Once you look under the top line, the whole thing is a story about a handful of companies swallowing almost everything.
The size cutoff tells it cleanly. In PitchBook’s numbers, rounds of 100 million dollars and up now account for 87.5 percent of all the capital going into US startups. In 2024 that figure was 56.2 percent. In 2025 it was 66.9 percent. Which means everything under 100 million, the normal-sized round that most companies actually raise, fell from a third of the market to 12.5 percent in a single year, according to SiliconANGLE’s breakdown of the same PitchBook Monitor. Cut by nearly two thirds. The mid-market’s share of the money did not shrink. It caved in.
One deal makes the point better than any chart. Anthropic raised 65 billion dollars in a single Series H in Q2 2026, at a post-money valuation of 965 billion. Against Crunchbase’s North American total of 137.2 billion for the quarter, that one round was close to half of all North American venture investment. One company. And more than 70 percent of global venture money in the quarter went to AI companies, up from a little under half just a year earlier. The concentration is not a footnote to the boom. The concentration is the boom.
Worth being precise about what that round actually was, because the framing flatters it: about 15 billion of the 65 was previously committed hyperscaler money, 5 billion from Amazon and 10 from Google, arriving under a new label. Still the second-largest venture round ever assembled, behind OpenAI’s own 122 billion dollar financing one quarter earlier. Just not 65 billion of newly persuaded capital.
And this money does not stay private for long. Anthropic filed a confidential draft S-1 with the SEC on June 1, so the round that ate close to half a quarter of North American venture is already pointed at a public ticker. The party moves indoors and then it sells tickets.
Meanwhile, at the stage where most of you actually live, the picture is thin. Crunchbase’s North American breakdown for Q2 has late-stage investors deploying 101 billion dollars. Seed startups, all of them combined, got 4.9 billion, down 15 percent from the prior quarter and down 27 percent from a year ago. That number will get revised up as late seed deals get logged, which Crunchbase says outright. It will not get revised up enough to matter. This is the same split I wrote about when a single quarter hit 300 billion dollars and four companies took most of it, except now we have six months of data confirming it was not a one-quarter fluke.
And here is where I have to argue against myself, because the same report says something that complicates the story. North American early-stage funding hit its highest level in more than three years in Q2 2026, just over 31 billion dollars, nearly double where it was a year ago. Globally, funding rose across every stage. So the honest version of my claim is narrower than the one I wanted to make: the mid-market’s share collapsed and seed dollars genuinely fell, but the floor did not drop out everywhere at once. If you are at Series A in a decent sector, the market is more open than this article’s tone implies. If you are at seed, or raising a boring round in a boring category, it is exactly as bad as it feels.
What this actually feels like if you are not an AI company
Say you run a perfectly good fintech, or a vertical SaaS tool, or a climate company, or a healthcare startup that is not wearing an AI costume. You raised a Series B in 2023 or 2024 on decent terms. You have real customers. You go out to raise your next round in this “record” market, and you cannot get a meeting to convert.
You are not imagining it, and you are not bad at your job. The money is real, it is just not pointed at you. The firms with the most dry powder, and per PitchBook the three biggest took 48.1 percent of all the venture capital raised in H1, are almost all aimed at the same category. And first-time funds, the new managers who historically write the weird, non-consensus, early checks that non-obvious companies depend on, are being formed at the slowest rate since 2016. Fewer new checkbooks, and the big ones all facing the same direction.
So the danger here is not envy. Envy is harmless. The danger is that you read a market that is not yours as if it were your weather forecast, and you make real decisions on borrowed optimism. You price your round like capital is everywhere. You plan to raise a bridge instead of earning one. You wait for a market that is, for you specifically, quietly having one of its tightest years in over a decade.
The moves that actually work in a market like this
None of this is a reason to quit. Record concentration at the top does not change the physics of a good business at the bottom. It just changes which advice is safe to follow. Here is what I would do.
Stop benchmarking your raise against a headline that is not about you. Your real comps are other non-AI companies raising right now, at your stage, in your sector. Not the Anthropic number. Anchoring to the wrong market is how a healthy company talks itself into a valuation nobody will meet and a timeline that runs out first.
Get to revenue, and treat it as the one number the record cannot touch. A concentrated venture market can ignore you. Your own profit and loss statement cannot. Every dollar of real revenue is a dollar you did not have to beg a distracted investor for, and it is the single most persuasive slide you will ever build. This is the whole logic behind the 90-day revenue rule that is quietly replacing MVP culture: prove someone will pay you fast, because the market will not carry you while you figure it out.
Take non-dilutive money seriously, not as a consolation prize but as a strategy. Per the same PitchBook Monitor, US venture debt ran to 64.7 billion dollars in the first half of 2026, across 280 loans, and if you are outside AI, that pool probably matters more to your runway math than the euphoria at the top ever will. Read that number the same way you should read the equity one, though: a single roughly 20 billion dollar SpaceX refinancing does a large share of the work in it, so the money actually available to a normal company is a lot smaller than 64.7 billion sounds. Revenue-based financing, grants, customer prepayments, a real annual contract paid up front. Boring money that does not require an AI narrative and does not price your company against a bubble.
Use AI as an efficiency layer, not a disguise. The wrong move is to paint “AI-native” on slide one to chase the 86 percent. Investors chasing that theme can smell a costume, and you will be competing head-on with actual labs. The right move is to use the collapsing cost of building, which is real and available to everyone now, to need less capital in the first place. Ship with a smaller team. Get to breakeven on less. Let AI shrink your burn instead of inflating your pitch.
And assume the comfortable middle is losing its claim on the money. The 100-million-and-up rounds took 87.5 percent of the capital, and the sensible mid-sized round’s share of the market got hollowed out, which is exactly the pattern I broke down when the safest pre-seed round became the hardest one to raise. Pick an end on purpose. Go genuinely lean and prove demand cheaply, or have a story big and fundable enough to earn a real seat at the top table. The one position that gets you killed now is the default middle, the round you write down out of habit because it is the number everyone used to raise.
The record is real. It is just not addressed to you.
I am not telling you the boom is fake. It is very real, and a few companies are going to define the next decade with the money they just raised. I am telling you the boom is small, in the sense that it fits inside a handful of buildings, and the headline was never a message to you.
The healthiest thing a founder can do this year is read the record for what it is, a description of a party happening in two houses on one street, and then go build the company that survives whether or not the check ever shows up. Because for most of you, it will not. And here is the part worth sitting with: that was still true in the best funding year the industry has ever had.